
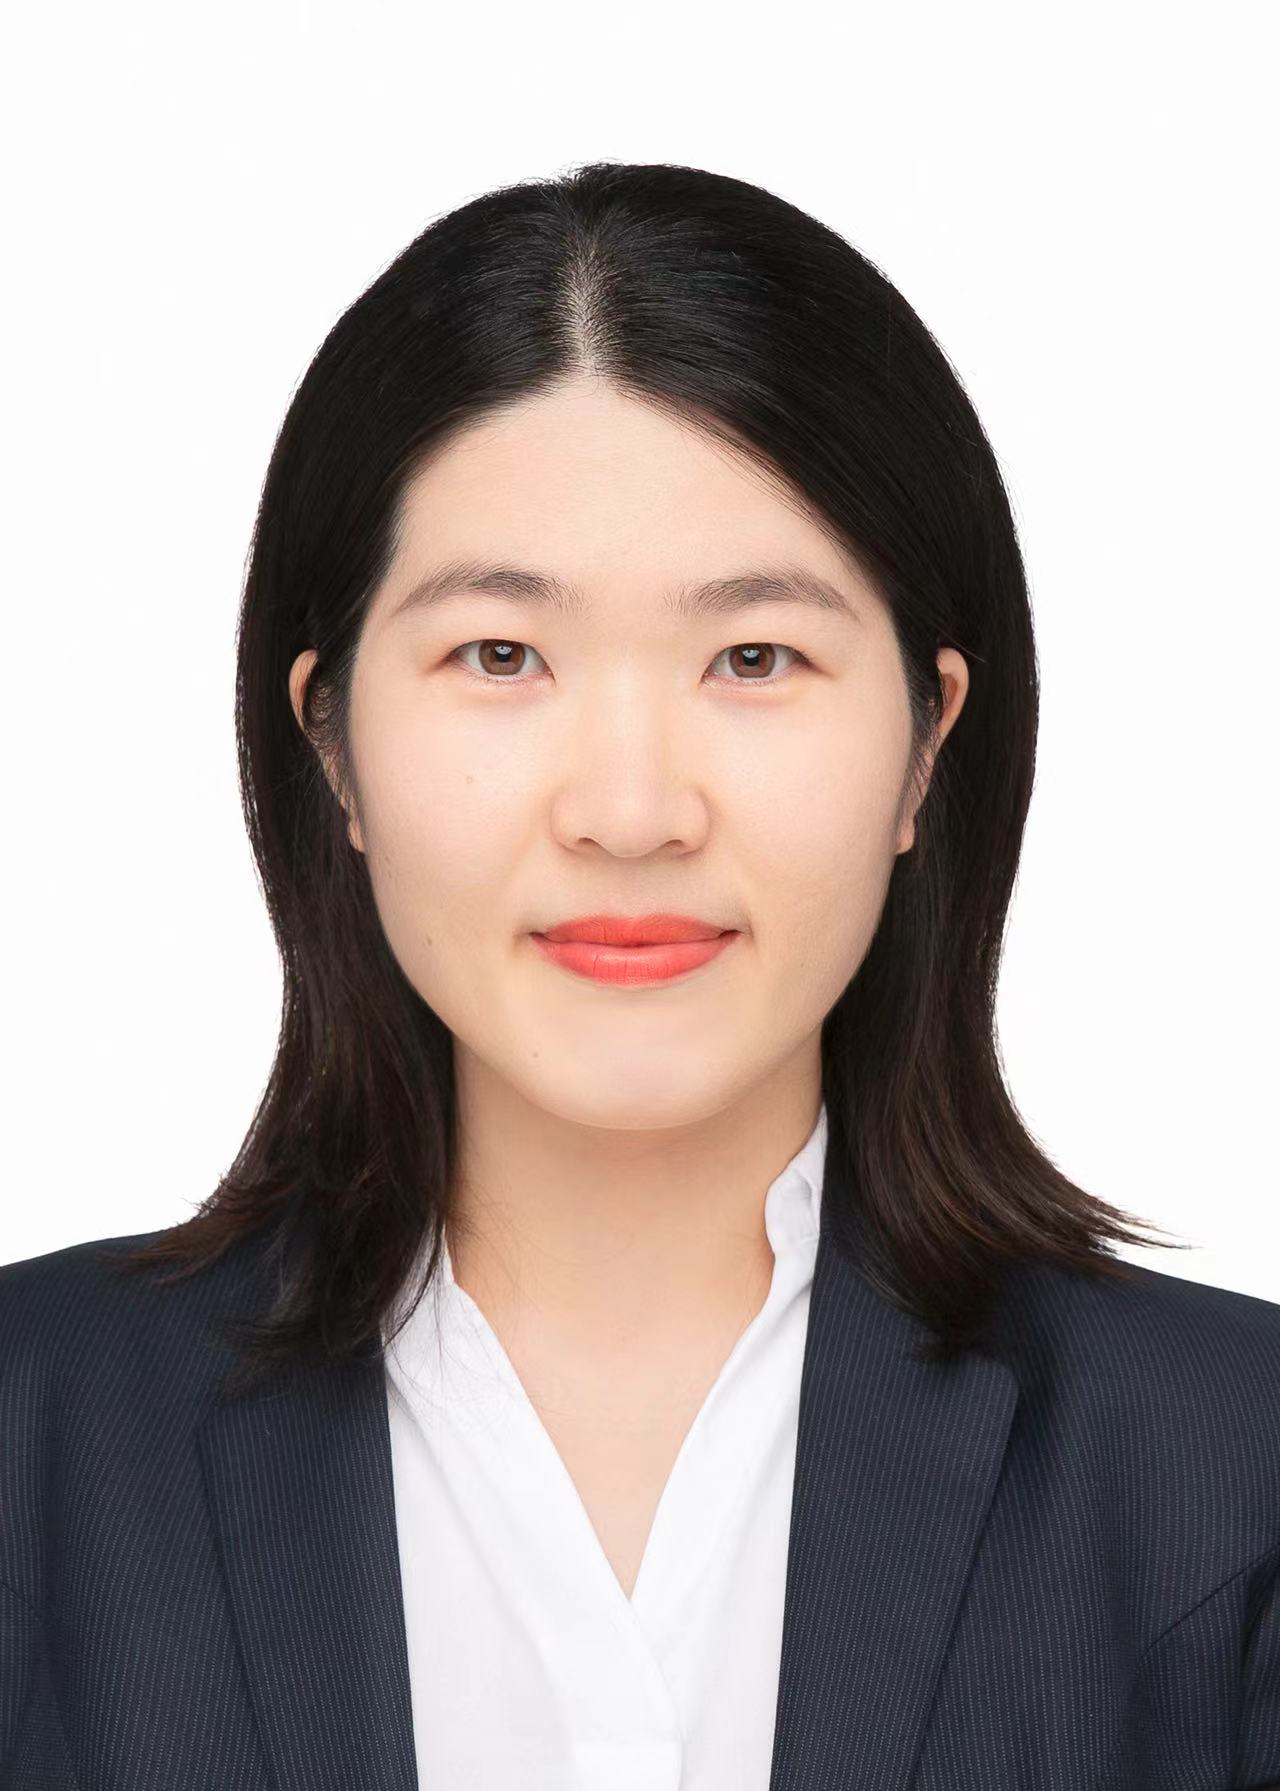
王莹
- 办公室:明德主楼943
- 职称/职务:副教授
- 办公电话:010-82500289
- 所属教研室:计量与数量经济学系-计量经济学教研室
- 电子邮箱:yingwang.econ AT ruc.edu.cn
- 研究领域:理论计量经济学,时间序列数据分析,高维数据因子模型
个人简介
王莹,北京大学经济学博士,新西兰奥克兰大学经济学博士后,威尼斯9499登录吴玉章青年学者,入选教育部长江学者奖励计划青年项目。主要从事理论计量经济学研究工作,关注变系数模型、非平稳时间序列数据分析和高维数据因子模型等方向。在Journal of Econometrics, Econometric Theory等高水平期刊发表论文十余篇。主持两项国家自然科学基金项目。
工作经历
2021-至今:威尼斯9499登录副教授
2020-2021:威尼斯9499登录讲师
2017-2020:奥克兰大学经济系博士后
2020-2021:威尼斯9499登录讲师
2017-2020:奥克兰大学经济系博士后
教育背景
经济学博士, 北京大学,2012-2017
统计学学士,山东大学,2008-2012
统计学学士,山东大学,2008-2012
讲授课程
本科生《计量经济学》《时间序列分析》,研究生《时间序列分析》
期刊论文
11. Wang Q, P. C. B. Phillips, Wang Y. 2026. New Asymptotics Applied to Functional Coefficient Regression and Climate Sensitivity Analysis. Econometric Theory.
10. Wang, Y., & Phillips, P. C. 2025. Limit theory for local polynomial estimation of functional coefficient models with possibly integrated regressors. Journal of Econometrics, 249, 106007.
9. Wang, X., Sui, X., Wang, Y., & Zhang, X. 2025. A Randomised Test to Distinguish Time‐Varying Coefficient Models. Oxford Bulletin of Economics and Statistics.
8. Wang, Y., Phillips, P. C., & Tu, Y. 2025. Limit theory and inference in non-cointegrated functional coefficient regression. Journal of Econometrics, 249, 105996.
7. Phillips*, P.C.B. and Wang, Y., 2023. “When Bias Contributes to Variance: True Limit Theory in Functional Coefficient Cointegrating Regression.” Journal of Econometrics, 232(2), 469-489.
6. Phillips*, P.C.B. and Wang, Y., 2023. “Limit Theory for Locally Flat Functional Coefficient Regression.” Econometric Theory, 39(5), 900-949.
5. Tu, Y. and Wang*, Y., 2022. “Spurious Functional-coefficient Regression Models and Robust Inference with Marginal Integration.” Journal of Econometrics, 229(2), 396-421.
4. Phillips*, P.C.B. and Wang, Y., 2022. “Functional coefficient panel modeling with communal smoothing covariates.” Journal of Econometrics, 227(2), 371-407.
3. Tu, Y. and Wang*, Y., 2020. “Adaptive estimation of heteroskedastic functional-coefficient regressions with an application to fiscal policy evaluation on asset markets.” Econometric Reviews, 39:3, 299-318.
2. Tu, Y. and Wang*, Y., 2019. “Functional Coefficient Cointegration Models Subject to Time–Varying Volatility with an Application to the Purchasing Power Parity.” Oxford Bulletin of Economics and Statistics, 81:6, 1401-1423.
1. Wang, Y., Tu*, Y. and Chen, S.X., 2016. “Improving Inflation Prediction with the Quantity Theory.” Economics Letters, 149, 112-115.
10. Wang, Y., & Phillips, P. C. 2025. Limit theory for local polynomial estimation of functional coefficient models with possibly integrated regressors. Journal of Econometrics, 249, 106007.
9. Wang, X., Sui, X., Wang, Y., & Zhang, X. 2025. A Randomised Test to Distinguish Time‐Varying Coefficient Models. Oxford Bulletin of Economics and Statistics.
8. Wang, Y., Phillips, P. C., & Tu, Y. 2025. Limit theory and inference in non-cointegrated functional coefficient regression. Journal of Econometrics, 249, 105996.
7. Phillips*, P.C.B. and Wang, Y., 2023. “When Bias Contributes to Variance: True Limit Theory in Functional Coefficient Cointegrating Regression.” Journal of Econometrics, 232(2), 469-489.
6. Phillips*, P.C.B. and Wang, Y., 2023. “Limit Theory for Locally Flat Functional Coefficient Regression.” Econometric Theory, 39(5), 900-949.
5. Tu, Y. and Wang*, Y., 2022. “Spurious Functional-coefficient Regression Models and Robust Inference with Marginal Integration.” Journal of Econometrics, 229(2), 396-421.
4. Phillips*, P.C.B. and Wang, Y., 2022. “Functional coefficient panel modeling with communal smoothing covariates.” Journal of Econometrics, 227(2), 371-407.
3. Tu, Y. and Wang*, Y., 2020. “Adaptive estimation of heteroskedastic functional-coefficient regressions with an application to fiscal policy evaluation on asset markets.” Econometric Reviews, 39:3, 299-318.
2. Tu, Y. and Wang*, Y., 2019. “Functional Coefficient Cointegration Models Subject to Time–Varying Volatility with an Application to the Purchasing Power Parity.” Oxford Bulletin of Economics and Statistics, 81:6, 1401-1423.
1. Wang, Y., Tu*, Y. and Chen, S.X., 2016. “Improving Inflation Prediction with the Quantity Theory.” Economics Letters, 149, 112-115.
科研项目
1,“平稳和非平稳数据的混合因子模型:理论与应用”,国家自然科学基金面上项目,主持,2026-2029.
2, “变系数回归模型中的伪回归问题:理论与实践”,国家自然科学基金青年项目,主持,已结项,2022-2024.
3,“非线性交互效应面板回归模型及其在项目评估中的应用”,国家自然科学基金面上项目,参与,2024-2027.
2, “变系数回归模型中的伪回归问题:理论与实践”,国家自然科学基金青年项目,主持,已结项,2022-2024.
3,“非线性交互效应面板回归模型及其在项目评估中的应用”,国家自然科学基金面上项目,参与,2024-2027.
匿名审稿
Econometric Theory, Economic Modelling, Advances in Econometrics, Empirical Economics, Journal of Quantitative Economics, New Zealand Economic Papers,《管理科学学报》